Nvidia-linked data center seeks $4.54 billion in high-yield bond market
A Nvidia-linked data center project in Nevada is returning to the high-yield debt market for another $4.54 billion. The money will go toward building the 200-megawatt site and its substation, and toward reimbursing part of the equity already invested. For the market, it is another test: are investors willing to keep financing AI infrastructure after a series of record offerings in April?
AI-processed from Bloomberg Tech; edited by Hamidun News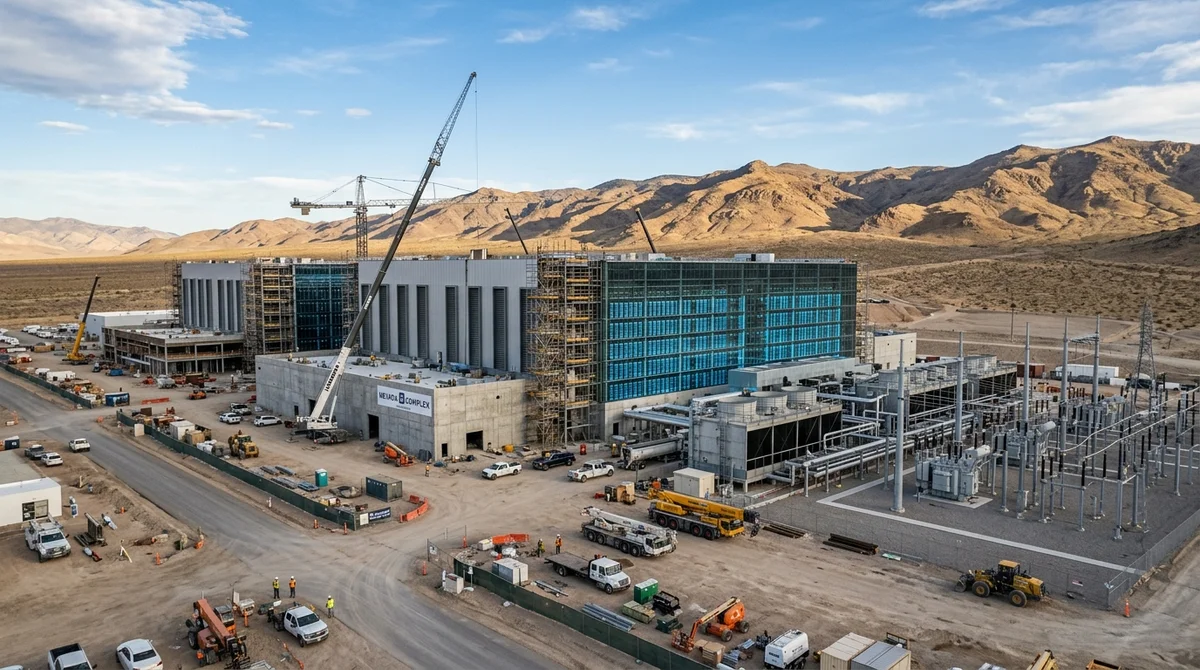
The AI infrastructure boom is moving further from tech promises and into the world of big debt: a vehicle tied to a data center project that Nvidia is expected to lease is trying to raise another $4.54 billion in the high-yield bond market. This is not a startup with a pitch deck, but a concrete construction project in Nevada: a 200-megawatt facility with a substation, meant to give Nvidia new computing capacity. The issuer is linked to Tract Capital Management and Fleet Data Centers.
According to the terms being discussed with investors, these are five-year notes with yield guidance in the upper part of the 6% range. The proceeds are intended to fund part of the construction and to reimburse equity investments already made. In other words, the project is not starting from zero: the owners' capital went in first, and now the developer is trying to shift a significant share of the load onto the debt market.
This is not the first attempt to borrow against the same asset. Back in February 2026, the developer raised $3.8 billion in a debut high-yield bond offering for this project. Interest was very strong then: according to market data, orders reached roughly $14 billion. That round showed investors were ready to lend to AI infrastructure even with a speculative credit profile, provided the project had a clear tenant and credible economics for future utilization. The new deal effectively tests whether that appetite survived the wave of similar offerings in April.
Context matters here. In 2026, the high-yield market quickly became one of the main channels for financing the US AI buildout. Companies tied to data center construction have already raised more than $22 billion this year through risky bonds. In recent weeks alone, the market has seen several large deals: a Google-linked project sold a record $5.7 billion, Core Scientific raised $3.3 billion, and Edged Compute raised $1.3 billion. Investors have effectively started buying not just the debt of individual companies, but a stake in future demand for computing capacity.
The reason is simple: demand for AI services has run up against not only chips but physical infrastructure. Developers need sites, electricity, cooling, network connectivity and the ability to bring all of it into operation quickly. For the market, this means a new asset category that sits somewhere between real estate, energy and technology capex.
It is also a telling moment for Nvidia. The company is becoming not just a GPU supplier but an anchor tenant of projects for which multibillion-dollar debt financing is raised in advance.
Money for such projects remains expensive, though. Yields on recent deals in the sector have been noticeably above the average for comparable bonds: investors demand a premium for construction risk, dependence on delivery schedules and concentration on one or two large customers. To make such deals more attractive, issuers sometimes offer extra protection, for example accelerated repayment of part of the debt over the life of the issue. That is an important signal: enthusiasm in the market exists, but it is not unconditional. Bond buyers are ready to finance the AI boom only if they see concrete safeguards, a clear payment structure and strong counterparties on the tenant side.
The Nevada project has what is now valued most: large scale, a defined site, a power component in the form of a substation, and a link to Nvidia as the future user of the capacity. So the attempt to borrow another $4.54 billion looks less like an oddity and more like a continuation of a new template. Developers are not assembling classic project finance over years of approvals, but fast market capital against demand already reserved by AI companies.
The main takeaway: the AI boom has fully entered a phase where its scale is measured not only by the number of models and chips, but by the size of the debt market willing to subscribe to it. If the deal succeeds, it will reinforce the idea that the capital market still believes in a long-term shortage of computing infrastructure and is ready to fund new campuses even at speculative rates. If demand is weaker, the market will get its first signal that the wave of AI debt is starting to hit the limits of investor appetite.
- Nov 2, 2026TensorFold 1.2.0 boosts Qwen3.8-27B throughput on M3 Ultra by 44.2% at 16 streams
- Nov 1, 2026Local models lose to Opus and Codex: 0.21 on a MacBook versus 1.00 for Codex
- Nov 1, 2026Habr author fine-tunes YOLOv8l on dental X-rays and pushes mAP50 to 0.642
- Nov 1, 2026Voice bots built on LLMs turn to Jev, a fast classifier, for decisions in 200–500 ms
Test Frontier LLMs & Autonomous Agents in One Workspace
Run Claude Opus 5.5, GPT-6, Gemini 3.1, and DeepSeek side-by-side in Nomad AI (nomadnet.ai) — unified model routing, deep research, and multimodal workflows under one subscription.
The AI world, distilled — once a week
Seven stories that actually mattered, hand-picked. No noise, no reposts, no press releases.
Done! Check your inbox for a confirmation.