Visa readies its payments infrastructure for transactions launched by AI agents
Visa has begun preparing bank infrastructure for payments that AI agents can launch on a customer's behalf. In Europe, the company is testing its Agentic Ready program with Commerzbank, DZ Bank and other issuers. The banks are checking tokenization, authentication and consent controls so that an agent can search for a product, compare prices and pay for it within set limits, without manual confirmation of every transaction. The program is not a standalone consumer service but a working environment for banks and payment partners.
AI-processed from AI News; edited by Hamidun News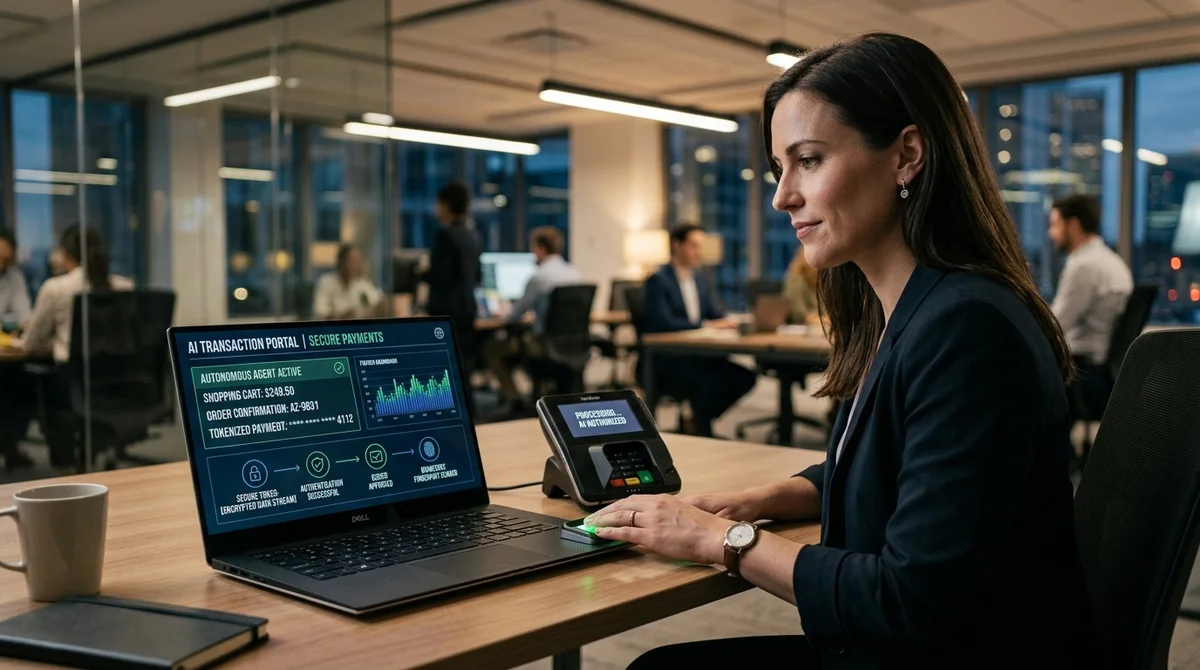
Visa has begun rebuilding its payments infrastructure for a scenario in which a purchase is initiated not by a person but by an AI agent. The company is already testing in Europe how such transactions can be processed safely without breaking established banking processes.
What Visa is testing
On 17 March 2026, the company launched the Visa Agentic Ready program in Europe. It is not a standalone consumer service but a working environment for banks and payment partners, who need to work out how to handle transactions initiated by software rather than by a person in an app or on a website.
The first wave includes more than twenty issuers and partners, among them Commerzbank, DZ Bank, Barclays, HSBC UK, Revolut and Banco Santander. The tests run together with Visa and selected merchants in a controlled environment that is already close to real conditions.
In essence, Visa is preparing for a model in which AI does not merely suggest what to buy but completes the purchase. A user or a company sets the goal, constraints and rules, and the agent finds the right product, compares options and launches the payment on its own. For card networks this is a significant shift: until now, a payment almost always began with an explicit human action, whereas now the initiator can be software. That changes the very point at which a bank must verify consent and the limits of authority.
"The more AI agents influence how people choose and buy goods, the faster payments must change too,"
Visa Europe said.
How it is supposed to work
Today a card transaction rests on simple logic: there is a specific cardholder, their intent and their confirmation of the purchase. In the agentic commerce model, a person still sets the intent, but part of the operational work passes to the agent. For example, it can monitor stocks of consumables, look for the best price within a set limit and place an order without a manual click each time.
Banco Santander has already demonstrated a practical scenario in which a book purchase was completed in a live environment using a Visa card.
Inside Agentic Ready, banks are testing not a single function but the entire path of such a transaction:
- card binding and token issuance for the agent's actions
- authentication through modern mechanisms such as passkeys and biometrics
- payment authorization that accounts for limits, rules and purchase type
- recording of consent, an action log and control of disputed transactions
- how the transaction behaves with real merchants, not only in a test sandbox
Visa describes this as a trust layer, where tokens, identity, risk models and user restrictions converge. The idea is that the agent does not get a "free card" but operates within a narrow corridor of authority. If a person has allowed a search for airline tickets up to a certain amount, or regular restocking of office supplies, the system must be able to verify that specific context, not merely the presence of a valid card.
Where the bottlenecks are
The main question is not whether AI can press the "pay" button. The main question is how to prove to the bank and the payment network that the agent is genuinely acting on behalf of a specific customer, within their consent and without exceeding its authority. Hence the interest in tokenization, biometric authentication, action logs and additional rules on the issuer side. Commerzbank and DZ Bank are testing exactly how to build such scenarios into existing processes without conflicting with compliance requirements.
There is a practical side too. If an agent picks the wrong item, buys at an unexpected price or strays outside the permitted category, the bank will still have to handle the dispute, reconstruct the chain of actions and settle the question of liability. So the current stage is not a mass launch of "autonomous purchasing for everyone" but the setup of infrastructure, auditing and control. This approach is especially interesting for corporate procurement: it can remove part of the routine, but it also demands very clear limits and rules.
What this means
The payments market is preparing for the moment when AI becomes not an adviser but a full participant in a transaction. If Visa's pilots succeed, banks will begin issuing agents limited, verifiable payment authority for routine purchases.
And this is no longer a distant concept: on 29 April 2026, Visa announced the expansion of Agentic Ready beyond Europe, which shows how quickly the topic is moving from experiment to industry standard.
- Nov 2, 2026Karpathy builds a YouTube clone with 6454 videos from Hacker News recommendations in two hours
- Nov 2, 2026Karpathy used Claude to build HackerTube from 6,454 videos recommended on Hacker News
- Nov 2, 2026Arca gives AI agents finance tasks lasting up to 10 days, but leaves the trades to humans
- Nov 2, 2026DeepSeek open-sources Super-agent prototype: p95 task completion time of 15.7 minutes vs. 29.5
Key Questions Answered
What Visa is testing?
On 17 March 2026, the company launched the Visa Agentic Ready program in Europe. It is not a standalone consumer service but a working environment for banks and payment partners, who need to work out how to handle transactions initiated by software rather than by a person in an app or on a website. The first wave includes more than twenty issuers and partners, among them Commerzbank, DZ Bank, Barclays, HSBC UK, Revolut and Banco Santander. The tests run together with Visa and selected merchants in a controlled environment that is already close to real conditions. In essence
How it is supposed to work?
Today a card transaction rests on simple logic: there is a specific cardholder, their intent and their confirmation of the purchase. In the agentic commerce model, a person still sets the intent, but part of the operational work passes to the agent. For example, it can monitor stocks of consumables, look for the best price within a set limit and place an order without a manual click each time. Banco Santander has already demonstrated a practical scenario in which a book purchase was completed in a live environment using a Visa card. Inside Agentic Ready, banks are testing n
Where the bottlenecks are?
The main question is not whether AI can press the "pay" button. The main question is how to prove to the bank and the payment network that the agent is genuinely acting on behalf of a specific customer, within their consent and without exceeding its authority. Hence the interest in tokenization, biometric authentication, action logs and additional rules on the issuer side. Commerzbank and DZ Bank are testing exactly how to build such scenarios into existing processes without conflicting with compliance requirements. There is a practical side too. If an agent picks the wrong
Test Frontier LLMs & Autonomous Agents in One Workspace
Run Claude Opus 5.5, GPT-6, Gemini 3.1, and DeepSeek side-by-side in Nomad AI (nomadnet.ai) — unified model routing, deep research, and multimodal workflows under one subscription.
The AI world, distilled — once a week
Seven stories that actually mattered, hand-picked. No noise, no reposts, no press releases.
Done! Check your inbox for a confirmation.