Meta spends on AI like a hyperscaler but doesn't show Amazon and Google's growth
Meta is raising the stakes on AI and infrastructure again, but the market doesn't see the same quality of returns from the company as from cloud giants. Capital expenditures up to $145 billion look too bold against the weak link between these investments and clear revenue growth. Management's cautious tone on the investor call only strengthened doubts.
AI-processed from Bloomberg Tech; edited by Hamidun News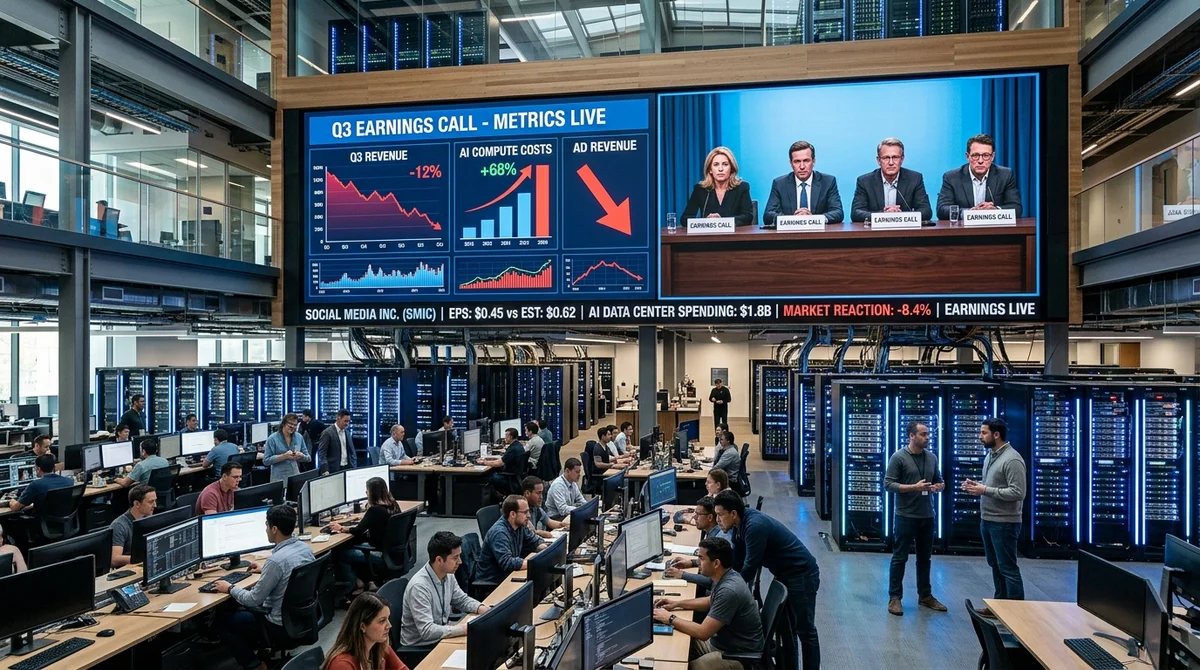
Where the Criticism Lies
Meta positions itself as a major player in the cloud infrastructure arms race alongside Amazon and Google. But there's a catch: the company isn't showing comparable growth metrics. Over the past three years, Meta's capital expenditure has grown from $17 billion to $25 billion annually. Meanwhile, AWS and Google Cloud continue expanding their revenue and customer bases at steady rates. Meta's problem is that it's spending like a hyperscaler but its financial results don't reflect the returns investors expect from such investments.
Why the Market Is Nervous
Investors are cautious because Meta hasn't clearly articulated how its massive AI investments translate into revenue growth. The company's management tone has been notably conservative—CFO Susan Li recently stated that capex may remain at "elevated levels" for the foreseeable future. This messaging creates uncertainty: Are these investments creating competitive moats? Will they drive ad-tech improvements that boost revenue?
The market is also watching how much these expenditures impact profitability. Even as Meta reports strong earnings, rising capex raises questions about sustainability and long-term returns.
Where the Money Goes
Meta's capital spending encompasses several categories:
- Data center infrastructure for training and inference of large language models
- GPU procurement (Nvidia chips dominate, with some custom silicon in development)
- Cooling and power systems to support massive computational demands
- Content moderation and safety infrastructure powered by AI
- Metaverse development and hardware (VR headsets, AR glasses)
The bulk of spending focuses on compute capacity. Meta is building redundancy and geographic distribution to support global inference at scale. This is necessary but costly.
What This Means
Meta faces a metrics problem. The company needs to demonstrate that its $25 billion annual capex translates into measurable business outcomes—whether that's improved ad-targeting, better content recommendations, reduced moderation costs, or new revenue streams. Until those connections become clear, Wall Street will remain skeptical.
The question isn't whether Meta should invest in AI. It should. The question is whether the company can show the market that these investments generate returns proportional to their scale. For now, Meta is spending like a hyperscaler but communicating like a company still figuring out the payoff.
- Oct 28, 2026Wired Tested 6 AI Agents in a Day: Dots Leads, Gemini Spark Fails at Lunch
- Oct 28, 2026Anthropic files S-1 for IPO at $2 trillion valuation: 85% margin, profitable Q2
- Oct 28, 2026Meta releases Muse Spark Open: 816B parameters and the lead among US open-weight models
- Oct 28, 2026Switzerland's Apertus 1.5 Gains Vision, Hearing and a 262K-Token Context Window
Key Questions Answered
Where the Criticism Lies?
Meta positions itself as a major player in the cloud infrastructure arms race alongside Amazon and Google. But there's a catch: the company isn't showing comparable growth metrics. Over the past three years, Meta's capital expenditure has grown from $17 billion to $25 billion annually. Meanwhile, AWS and Google Cloud continue expanding their revenue and customer bases at steady rates. Meta's problem is that it's spending like a hyperscaler but its financial results don't reflect the returns investors expect from such investments.
Why the Market Is Nervous?
Investors are cautious because Meta hasn't clearly articulated how its massive AI investments translate into revenue growth. The company's management tone has been notably conservative—CFO Susan Li recently stated that capex may remain at "elevated levels" for the foreseeable future. This messaging creates uncertainty: Are these investments creating competitive moats? Will they drive ad-tech improvements that boost revenue? The market is also watching how much these expenditures impact profitability. Even as Meta reports strong earnings, rising capex raises questions about
Where the Money Goes?
Meta's capital spending encompasses several categories: Data center infrastructure for training and inference of large language models GPU procurement (Nvidia chips dominate, with some custom silicon in development) Cooling and power systems to support massive computational demands Content moderation and safety infrastructure powered by AI Metaverse development and hardware (VR headsets, AR glasses) The bulk of spending focuses on compute capacity. Meta is building redundancy and geographic distribution to support global inference at scale. This is necessary but costly.
Test Frontier LLMs & Autonomous Agents in One Workspace
Run Claude Opus 5.5, GPT-6, Gemini 3.1, and DeepSeek side-by-side in Nomad AI (nomadnet.ai) — unified model routing, deep research, and multimodal workflows under one subscription.
The AI world, distilled — once a week
Seven stories that actually mattered, hand-picked. No noise, no reposts, no press releases.
Done! Check your inbox for a confirmation.