Madison Air raised $2.23 billion in its IPO and bet on data center infrastructure
Madison Air went public and raised $2.23 billion — for the AI market, that signals investors are actively backing not only models, but also the infrastructure around data centers. Jill Wyant is now betting on growing demand for ventilation, filtration, and Terafabs projects needed to scale compute capacity.
AI-processed from Bloomberg Tech; edited by Hamidun News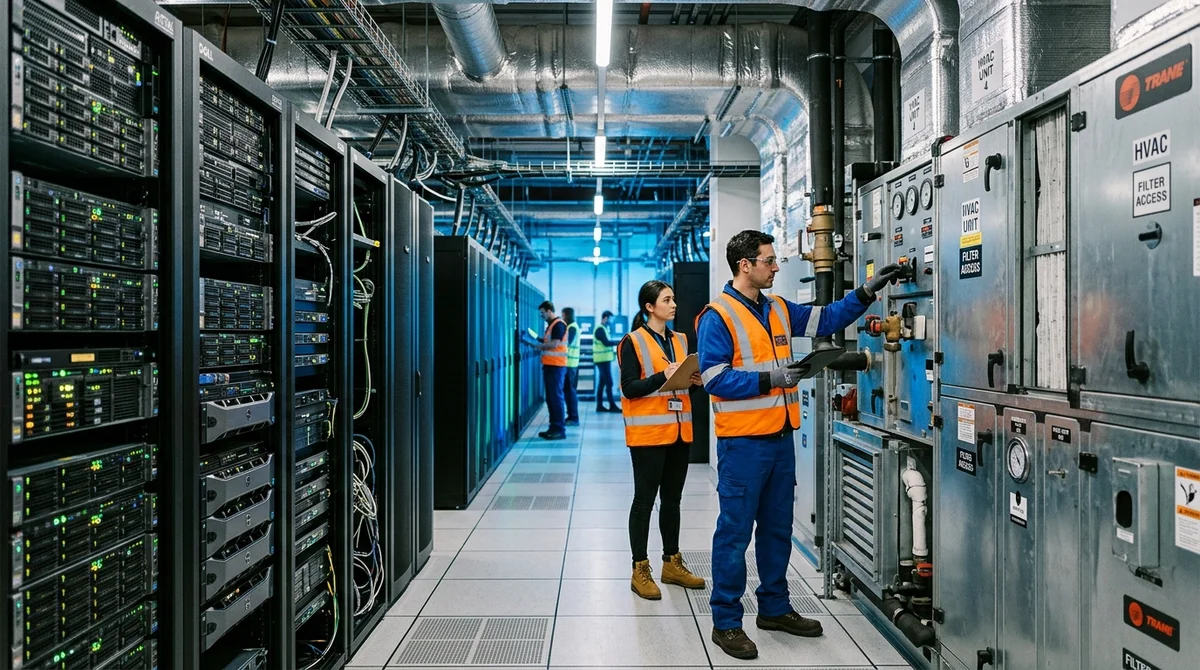
Madison Air raised $2.23 billion in an IPO and immediately became the focus of attention as one of the notable infrastructure beneficiaries of the AI boom. Jill Wyant, President and CEO of the company, linked further business growth to data center expansion and the construction of Terafabs during a discussion about the offering.
IPO as a Signal
The size of the offering matters not only for Madison Air itself. The market has long been seeking ways to profit from artificial intelligence not through another model or chatbot, but through more grounded segments with understandable revenue streams. Manufacturers of ventilation and filtration systems look here like classic "picks and shovels": when data centers grow, they need air, cooling, cleanliness, and a stable microclimate.
A major IPO shows that investors are ready to pay for such less visible but critical elements of the AI chain. For Madison Air, it's also a shift in the scale of perception. A company that was previously associated primarily with building engineering infrastructure is now increasingly viewed as a supplier for a new compute cycle.
Against the backdrop of the GPU race and construction of new facilities, this makes sense: the denser the computations, the higher the cost of errors in airflow, temperature, and environmental reliability. This makes such solutions part of the investment thesis, rather than just an engineering purchase.
Betting on Data Centers
Wyant's main thesis is that the window of opportunity opens precisely in data centers. AI workload dramatically raises engineering requirements for the facility: equipment runs denser, thermal load increases, and downtime becomes too costly. Against this background, ventilation and filtration stop being a secondary expense item and become part of productivity.
If server racks operate in an unstable environment, not only does cooling efficiency fall, but the predictability of the entire facility suffers. As rack density grows, the cost of such infrastructure only increases. Separately, during the interview, Terafabs came up—a direction that Madison Air links to further infrastructure scaling.
Even without detailed technical details from the conversation, it's clear that the company is betting not on one-off deliveries, but on a larger cycle of construction and equipping new capacity. For the market, this is an important nuance: winners can be not only data center owners, but also those who can quickly, serially, and reliably supply them with basic engineering components.
What Drives Growth
Interest in Madison Air is understandable: money flows to where AI turns into physical objects—buildings, server rooms, air delivery systems, filters, and service. This is no longer a story about a slick product presentation, but about years of CAPEX, contracts, and maintenance. If demand for compute continues to grow, infrastructure suppliers get a longer and clearer wave of revenue. This is the key shift for investors looking for a more tangible AI case.
- New data centers require ventilation and filtration already at the design stage.
- Existing facilities need to be upgraded for denser AI workloads.
- The reliability of engineering systems directly impacts uptime and downtime costs.
- Large construction programs create demand not for a single delivery, but for a series of projects.
- Infrastructure players can grow alongside the AI market without competing with model developers.
This is precisely why Madison Air's IPO can be read as a bet on the second tier of the AI economy. While public attention is fixed on OpenAI, Nvidia, and hyperscaler companies, capital is increasingly seeking those who ensure this entire ecosystem works at the hardware and building level. In such segments there is usually less hype, but more dependence on actual construction cycles and corporate budgets. It's here that long orders and recurring revenue often form.
What This Means
The AI market is gradually ceasing to be a story only about models and chips. Madison Air's successful IPO shows that the next wave of interest is going to suppliers of physical infrastructure—from ventilation to data center environment systems. For business, this is a signal to look broader: money and demand will settle not only in software, but in companies without which computational capacity simply cannot be scaled. Against the backdrop of the AI race, it's precisely such companies that can claim a stable share of the ecosystem's margin.
- Oct 28, 2026Keystone removes the model name from code: open-source LLM gateway adds 0.64 ms
- Oct 28, 2026Wired Tested 6 AI Agents in a Day: Dots Leads, Gemini Spark Fails at Lunch
- Oct 28, 2026Anthropic Turns Claude Code Into a Platform: Claude Mods Flip the Agent Harness
- Oct 28, 2026Liquid AI releases LFM2.5-24B-A2B: an agent model with 2B active parameters
Key Questions Answered
What are the key details on IPO as a Signal?
The size of the offering matters not only for Madison Air itself. The market has long been seeking ways to profit from artificial intelligence not through another model or chatbot, but through more grounded segments with understandable revenue streams. Manufacturers of ventilation and filtration systems look here like classic "picks and shovels": when data centers grow, they need air, cooling, cleanliness, and a stable microclimate. A major IPO shows that investors are ready to pay for such less visible but critical elements of the AI chain. For Madison Air, it's also a shi
What are the key details on Betting on Data Centers?
Wyant's main thesis is that the window of opportunity opens precisely in data centers. AI workload dramatically raises engineering requirements for the facility: equipment runs denser, thermal load increases, and downtime becomes too costly. Against this background, ventilation and filtration stop being a secondary expense item and become part of productivity. If server racks operate in an unstable environment, not only does cooling efficiency fall, but the predictability of the entire facility suffers. As rack density grows, the cost of such infrastructure only increases.
What Drives Growth?
Interest in Madison Air is understandable: money flows to where AI turns into physical objects—buildings, server rooms, air delivery systems, filters, and service. This is no longer a story about a slick product presentation, but about years of CAPEX, contracts, and maintenance. If demand for compute continues to grow, infrastructure suppliers get a longer and clearer wave of revenue. This is the key shift for investors looking for a more tangible AI case. New data centers require ventilation and filtration already at the design stage. Existing facilities need to be upgrade
Test Frontier LLMs & Autonomous Agents in One Workspace
Run Claude Opus 5.5, GPT-6, Gemini 3.1, and DeepSeek side-by-side in Nomad AI (nomadnet.ai) — unified model routing, deep research, and multimodal workflows under one subscription.
The AI world, distilled — once a week
Seven stories that actually mattered, hand-picked. No noise, no reposts, no press releases.
Done! Check your inbox for a confirmation.